VAT RETURN SERVICES FOR SMALL BUSINESSES

Support with accurate VAT records, calculations and submissions
VAT Returns are prepared using the bookkeeping records maintained throughout your VAT period. We help ensure those records are complete, organised and reviewed before your VAT Return is prepared.
Our VAT Return service can include:
- maintaining or reviewing your VAT records;
- checking that transactions have been recorded using the appropriate VAT treatment;
- reconciling relevant accounts;
- calculating the VAT due to HMRC or repayable to your business;
- preparing your VAT Return for approval; and
- submitting the approved return to HMRC using compatible software.
We start by understanding your business
Before beginning the work, we need to understand how your business operates and how VAT applies to its activities.
We may ask about:
- the goods or services your business provides;
- the types of customers and suppliers you work with;
- whether you trade within or outside the UK;
- the VAT rates normally used by your business;
- your VAT accounting periods; and
- whether you use a special VAT scheme.
This helps us understand what we should expect to see in your records and identify areas that may require further information.
We review your existing VAT position
If we are taking over your VAT bookkeeping or VAT Returns, we will first review the information already available.
We will normally require:
- your VAT registration details;
- access to your accounting software;
- your most recently submitted VAT Return;
- previous VAT calculations or reports for that return, where available;
- details of any VAT schemes being used;
- information about any outstanding VAT liabilities or repayments;
- correspondence received from HMRC concerning VAT; and
- details of any known errors or adjustments that still need to be considered.
Reviewing the previous return helps us understand the figures brought forward and maintain continuity between VAT periods.
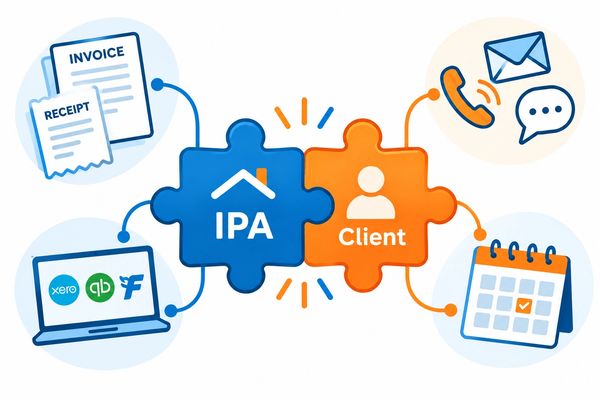
We agree how we will work together
Every business maintains its records differently. At the start, we'll agree a practical process for providing documents, answering questions and approving each VAT Return .
Depending on your business, you may provide information through:
- accounting software;
- receipt-capture software;
- digital copies of invoices and receipts;
- bank feeds or bank statements; and
- other supporting records relevant to your VAT transactions.
We will also agree when your records must be provided so there is sufficient time to complete the bookkeeping, resolve questions and prepare your return before the deadline.
Authorising IPA to act for your business
Before we can deal with HMRC on your behalf and submit VAT Returns for you, you will need to authorise IPA Bookkeeping & Accounting Ltd to act as your VAT agent.
We will normally start the authorisation process through our HMRC Agent Services Account and send you a secure HMRC authorisation link. HMRC refers to this process as the digital handshake.
WHAT YOU WILL NEED TO DO
When you receive the authorisation link from us, you will need to open it and sign in using the details you use for the relevant HMRC tax service. You may also be asked by HMRC to verify your identity before you can approve the authorisation. The authorisation link normally expires after 21 days, so it is important to complete the process within that time.
You must complete the authorisation yourself. Please do not send us your Government Gateway user ID, password, access codes or other HMRC sign-in credentials. HMRC states that these details must not be given to your agent or anyone else.
Once you have approved the authorisation, we can act as your VAT agent and deal with HMRC for the VAT services covered by your authorisation.
Authorising IPA Bookkeeping & Accounting Ltd to act as your VAT agent does not transfer responsibility for your VAT affairs to us. You remain legally responsible for your own tax affairs.
Before we submit a VAT Return on your behalf, we will provide the return information for you to review and approve as part of our VAT Return process.
Keep your VAT records up to date
Regular bookkeeping makes VAT Return preparation more manageable.
When records are maintained throughout the VAT period, it is easier to:
- identify missing invoices and receipts;
- check that sales and purchases have been recorded;
- investigate unusual transactions;
- resolve questions while the information is still recent;
- monitor the amount of VAT that may become payable; and
- avoid a last-minute rush before the submission deadline.
VAT-registered businesses are generally required to keep specified VAT records digitally and submit their VAT Returns using compatible software, unless HMRC has granted an exemption.
Send documents as you receive them
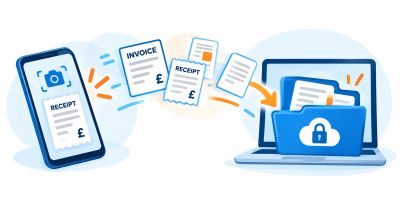
Please provide your sales invoices, purchase invoices, receipts and other VAT documents as they arise rather than waiting until the end of the VAT period.
Depending on your activities, we may also need:
- credit notes;
- import VAT certificates and statements;
- postponed import VAT statements;
- export documents;
- evidence supporting zero-rated or exempt transactions;
- mileage or fuel records;
- records of business and private use;
- finance agreements; and
- information about asset purchases or disposals.
Send documents as you receive them. Having the correct supporting evidence is important because VAT cannot always be reclaimed from a bank transaction alone.
Your VAT bookkeeping is brought up to date
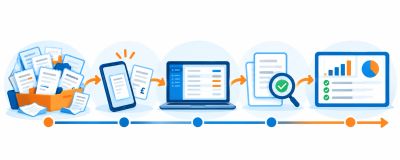
Throughout the VAT period, we will process or review the relevant transactions in your accounting software.
This may include:
- recording sales and purchase transactions;
- checking the VAT codes applied;
- matching payments and receipts;
- reconciling bank and relevant control accounts;
- checking for duplicate or missing entries;
- reviewing outstanding balances; and
- recording agreed VAT adjustments.
Accurate bookkeeping provides the foundation for an accurate VAT Return.
We identify questions as we go
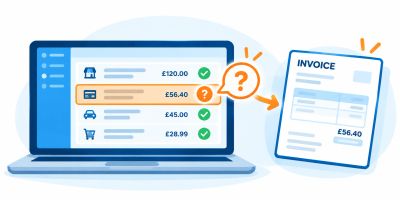
Sometimes a transaction cannot be treated correctly without additional information.
For example, we may need to ask:
- what a particular purchase was for;
- whether an expense had any private use;
- whether a supplier invoice is available;
- where a customer or supplier is located;
- whether an amount includes VAT;
- whether goods or services were imported or exported; or
- whether a transaction relates to the current VAT period.
Responding to questions promptly helps us complete the records and reduces delays when the VAT Return is due.
Monitoring your potential VAT liability
Up-to-date records can give you a clearer indication of the VAT that may become payable before the return is due.
This can help you:
- set money aside for VAT;
- plan for the payment deadline;
- protect your business cash flow; and
- avoid treating VAT collected from customers as money available to spend.
The figure may change as further transactions, invoices or adjustments are recorded, but regular bookkeeping provides better visibility than waiting until the end of the quarter.
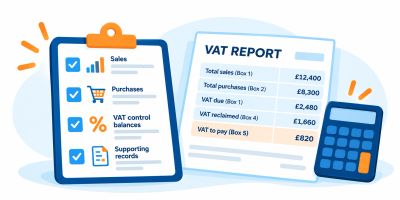
We review the VAT information
Once the bookkeeping for the period is complete, we carry out checks before preparing the return.
These may include:
- reviewing the VAT charged on sales;
- reviewing VAT reclaimed on purchases;
- checking transactions with unusual or missing VAT codes;
- considering relevant adjustments;
- comparing the figures with previous periods;
- reviewing larger or unexpected transactions; and
- checking that the VAT control account agrees with the return.
If anything appears unclear or inconsistent, we will raise it with you before finalising the figures.
Your VAT Return is prepared for approval
Once the bookkeeping for the VAT period has been completed and reviewed, we will prepare your VAT Return using the information recorded in your accounting software.
We will provide you with the figures and explain:
- whether the return shows VAT payable to HMRC or a repayment due to your business;
- the amount shown on the return;
- the submission and payment deadline;
- any significant adjustments included; and
- any important questions, estimates or assumptions.
You are responsible for checking the information and confirming that, to the best of your knowledge, it is complete and correct.
We will not submit the VAT Return until we have received your clear approval. Your approval must be provided in the agreed form, normally through our client portal, by email or through another recorded approval process.
We submit the approved return
Once we have received your approval, we will submit the VAT Return to HMRC using Making Tax Digital-compatible software.
We will confirm that the return has been submitted successfully and provide the relevant submission information for your records.
Most VAT Returns must be submitted—and any VAT due must reach HMRC—one calendar month and seven days after the end of the accounting period. Different deadlines can apply under some arrangements, including the Annual Accounting Scheme.
If we do not receive the required information, HMRC agent authorisation or approval before the agreed deadline, we may be unable to submit the return on time.
Paying VAT to HMRC is your responsibility
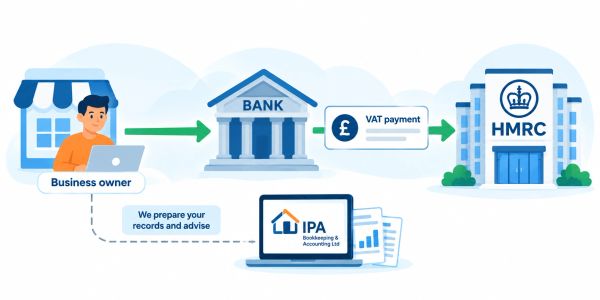
You are solely responsible for paying any VAT due to HMRC. IPA Bookkeeping & Accounting Ltd does not make or receive payments on behalf of clients and does not hold client money.
We do not:
- arrange or authorise payments from your bank account;
- accept money for onward payment to HMRC; or
- confirm that a payment has reached HMRC unless you provide appropriate evidence.
Once your VAT Return has been prepared, we will tell you:
- the amount shown as payable;
- the HMRC payment deadline; and
- the payment reference or other relevant payment information available to us.
You must arrange payment directly to HMRC using one of HMRC’s accepted payment methods. You are responsible for ensuring that:
- the correct amount is paid;
- the correct payment reference is used;
- sufficient funds are available; and
- the payment reaches HMRC by the deadline.
Submitting a VAT Return and paying the VAT due are separate obligations. Our submission of your VAT Return does not mean that payment has been made.
If you pay by Direct Debit, you remain responsible for checking that the arrangement is active, the bank details are correct and sufficient funds are available.
If your VAT Return shows a repayment
If the VAT Return shows that HMRC owes money to your business, any repayment will be made directly by HMRC to the bank account registered with HMRC, subject to HMRC’s checks.
IPA Bookkeeping & Accounting Ltd does not receive VAT repayments on behalf of clients and does not hold or transfer repayment funds.
You are responsible for ensuring that HMRC has the correct bank account details for your business.
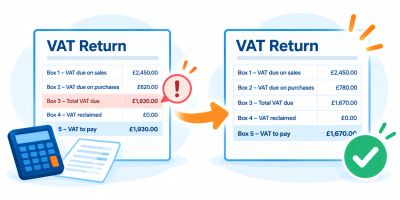
If earlier VAT records contain errors
If you believe a previous VAT Return may contain an error, please tell us as soon as possible.
We can review the available records, identify the difference and consider the appropriate next step. The method used to correct an error depends on matters including its value, age and circumstances. Some errors can be adjusted through a later VAT Return, while others must be disclosed separately to HMRC.
Additional work to investigate or correct earlier VAT periods may be quoted separately from the regular VAT Return service.
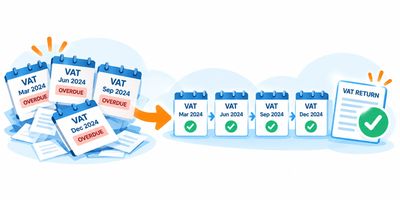
Behind with your VAT Returns?
If your VAT bookkeeping or returns have fallen behind, please contact us before trying to correct everything yourself.
We can begin by establishing:
- which VAT Returns are outstanding;
- what information is available;
- which records or documents are missing;
- whether HMRC has issued estimated assessments or penalties;
- whether earlier bookkeeping must be corrected; and
- what work is needed to bring the VAT position up to date.
We will then explain the proposed work and the information needed from you.
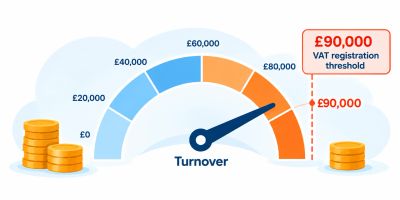
Not sure whether you need to register for VAT?
A business must generally register for VAT if its VAT-taxable turnover for the previous 12 months exceeds £90,000. Registration is also required if you expect your VAT-taxable turnover to exceed £90,000 in the next 30 days alone.
VAT-taxable turnover is generally calculated using the value of your taxable sales excluding VAT.
Add together the net value of your standard-rated, reduced-rated and zero-rated sales. Do not include the VAT charged to customers. VAT-exempt and outside-the-scope income is generally excluded.
VAT registration should be considered carefully because it affects pricing, record keeping, invoicing and reporting responsibilities.